Hurricane Claim Closed Without Payment? What to Do Next
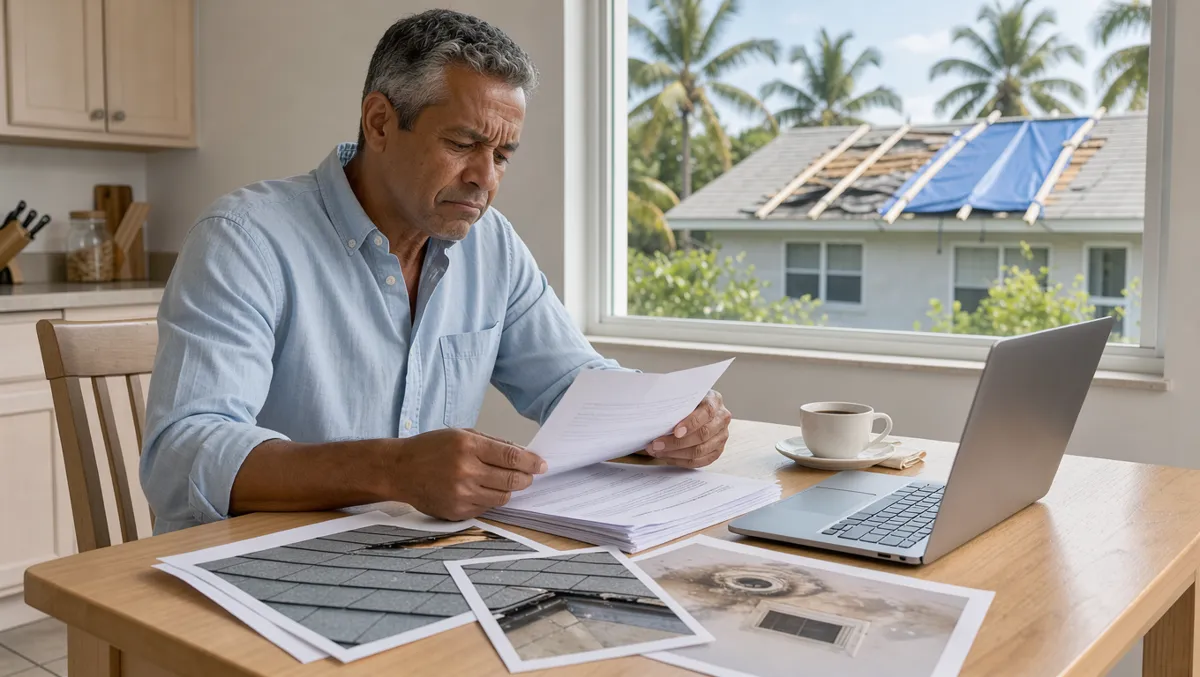
You filed your hurricane claim, waited, and then a letter showed up: claim closed, no payment. Maybe it says the damage is below your deductible. Maybe it says the damage was there before the storm. Maybe it does not say much at all. Do not assume that letter is the end of the road. Here is what our public adjusters tell Florida homeowners who call us with a closed claim.
1. Find Out Exactly Why It Was Closed
Ask your insurance company to explain the decision in writing, including the policy language it relied on. “Closed” can mean a lot of things. Some claims are closed for paperwork reasons, like a duplicate claim number or missing documents. Some are closed because the insurer’s estimate came in under the deductible. Some are closed because the insurer says the damage is not covered. Each one calls for a different response, so get the reason on paper.
Free claim review
Tell us what happened and a public adjuster will call you back. No recovery, no fee.
2. Get the Insurer’s Estimate and Reports
If the claim was closed as “below deductible,” ask for the adjuster’s full estimate and any engineer or inspection report. Go through it line by line against your own photos. Look for missing rooms, missed roof damage, short measurements and low prices. Damage that is easy to miss, like lifted shingles, water stains in the attic and swollen cabinets, often never makes it onto the insurer’s estimate.
3. Check Your Hurricane Deductible
Most Florida policies carry a separate hurricane deductible, usually a percentage of your dwelling coverage. Under Section 627.701 of the Florida Statutes, a hurricane deductible generally applies once per calendar year, not once per storm. If you already paid toward a hurricane deductible earlier in the same year, make sure your insurer counted it.
4. Reopen the Claim or File a Supplemental Claim
A closed claim is not always a dead claim. Under Section 627.70132 of the Florida Statutes, you generally have 1 year from the date of loss to report a new claim or reopen a claim, and 18 months from the date of loss to file a supplemental claim for damage or costs you find later. Send new photos, contractor estimates and anything the insurer missed, in writing, and keep copies. Do not wait until the last minute!
5. Know Your Rights and Your Options
- Florida’s Homeowner Claims Bill of Rights (Section 627.7142, Florida Statutes) lays out what your insurer must tell you and when.
- The Florida Department of Financial Services runs a residential property mediation program under Section 627.7015 of the Florida Statutes. For eligible residential claims, the insurer generally pays the mediator’s fee. Call the DFS consumer helpline at 1-877-693-5236 to ask about it.
- If your policy has an appraisal clause and the dispute is about the amount of the loss, you may be able to demand appraisal. Learn how umpires fit into that process.
- A licensed public adjuster can reinspect the property, build a detailed estimate and handle the back-and-forth with your insurer. The insurance company has its own adjusters. A public adjuster works for you. Not sure? Read should I hire a public adjuster?
Stay the Course
A closed claim can feel final, but many of them are not. Get the reason in writing, check the numbers, and move before the deadlines run out. If Hurricane Isaias damaged your home, our Hurricane Isaias claim page has more on what to do now, and our Florida hurricane claim guide covers the first steps after any storm.
Insurance Claim Consultants has helped property owners with hurricane claims since 1990. We have offices in Tampa and Panama City Beach, we work with homeowners in Pensacola, and we answer the phone 24/7 at (800) 572-7914.
Ronald F. Delo, Licensed Public Adjuster, Florida License A065774
This guide is general information, not legal advice. Every policy is different and Florida law changes, so check your own policy and the current statutes mentioned above.
SERVICES
CLAIM TYPES
Industry Affiliation


Advertisements
This advertisement is made under the public adjuster licensure of Ronald F. Delo Florida License Number: A065774
